// PODCAST

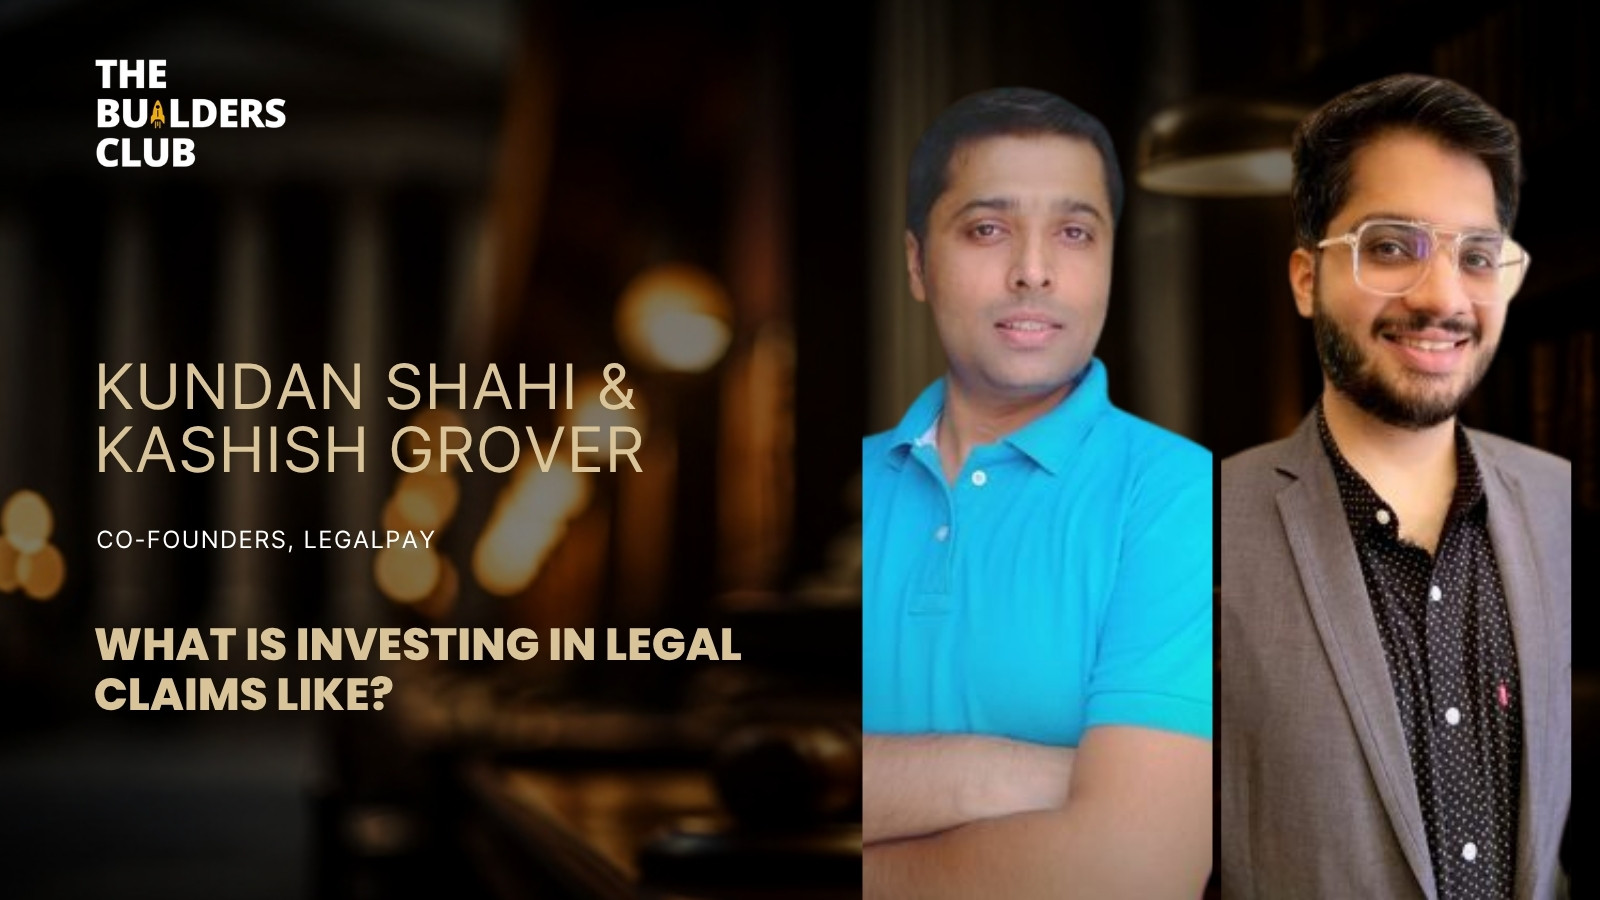
Litigation Finance in India: How Funders Back Legal Claims | Kundan and Kashish, LegalPay

Kundan and Kashish, the CEO and CIO of LegalPay, explain how litigation finance works in India. They cover underwriting, investor structures and why they focus on commercial claims between businesses.
Kundan and Kashish, LegalPay on The Builders Club Startup Founders Podcast
Advertisement

Imagine a business that is owed crores but cannot afford the years of legal fees needed to collect. That is the gap Kundan and Kashish, the CEO and CIO of LegalPay, set out to fill with litigation finance in India.

In this Builders Club Water Cooler conversation, the co-founders explain how a third party funds a legal claim, how they decide which cases to back and how investors can access the asset class.

What is litigation finance and how does it work in India? LegalPay’s core thesis

Kundan describes litigation finance as a practice where a third party invests in a legal claim. If the claim succeeds, the funder takes an agreed share of the recovery, and if it fails, the funder recovers nothing. The investment is non-recourse to the client.

LegalPay focuses on commercial claims between businesses, backed by heavy diligence and data. Kashish added that the model turns a previously private, family-office asset class into something more structured and accessible for investors.

  • Third-party funding. The funder pays costs and shares in the recovery only if the claim wins.
  • Businesses, not individuals. LegalPay avoids disputes between individuals and low-value cases.
  • Layered diligence. Legal, financial and lawyer-quality checks, plus a tech scoring model.
  • Structured investor pools. Capital goes into separate vehicles spread across several cases.

How did Kundan and Kashish start LegalPay?

Kundan said he is neither a lawyer, a finance professional nor a technologist. He came from a village in Bihar, worked in a data and process outsourcing firm supporting US insurers and learned about risk and underwriting there. After an accident gave him time to think, he left to start a legal-tech venture that tested litigation funding and shut in 2018, and he started LegalPay in late 2019.

Kashish, who has experience at Goldman Sachs and PwC and had his own food and beverage startup, was LegalPay’s first hire. Kundan brings the legal-system knowledge and Kashish the investing and strategy side.

How does litigation funding work for a business?

Kundan explained that litigation funding is a pain point for businesses that have a strong claim but not the cash to pursue it. A funder invests, and if the claim wins, shares in the recovery.

He said the Supreme Court of India has recognised that litigation funding is not barred, with only lawyers prevented from funding cases. The founders spent a long time convincing lawyers and others that it was legitimate.

  • The funder carries the cost, so the client does not need to pay up front.
  • The investment is non-recourse, so a lost case means no repayment.
  • Commercial terms are agreed in advance, not changed as a case nears closure.
  • The funder should not influence the bench or push the client to settle.

How does LegalPay decide which cases to fund?

Kundan listed four underwriting criteria: the merit of the claim, the chances of recovery, the skill of the legal team and the timeline. They generally prefer cases that should resolve in around three years. Kashish said they test the lawyer as well as the case, much like judging the jockey, not just the horse.

Kashish described a three-level diligence process, a 15-point-plus tech scoring model and an approval panel of experienced lawyers and professionals.

  1. Legal diligence, with documentary proof rather than personal testimony.
  2. Financial diligence of both the plaintiff and the opposing party.
  3. Review of the lawyers and their record on similar cases.
  4. Scoring by the in-house model, then review by an approval panel.

Why focus on B2B cases and not individuals?

The earlier venture went after all kinds of cases, and Kundan said that experience taught them what not to do. LegalPay avoids small claims and disputes where the parties are individuals, because claims, recovery and securitisation are easier to establish when the parties are businesses.

He added that businesses care about reputation and tend to settle. They stay with high courts, the Supreme Court and arbitration, where proceedings are more time-bound and transparent.

How can investors access this asset class?

Kashish said family offices and high-net-worth investors have long used litigation finance informally, and LegalPay formalises it through structured pools. They had also just launched a fund for upper-retail investors with ticket sizes from 25,000 rupees, which invests in arbitration cases.

Capital goes into separate limited liability partnership structures, and investors are the owners of the underlying assets rather than LegalPay holding their money. Each pool spreads money across about six to ten cases. The team described the returns and timelines they target, but these are their own figures and not advice.

How does LegalPay make money?

Kundan said LegalPay follows a private equity style model, with a 2 percent management fee on commitments and a 20 percent carry.

Is litigation finance regulated in India?

Kundan said there is no specific regulation, so the company self-regulates and follows the public policy limits recognised by the Supreme Court. He cited the push to make India an arbitration hub and said many Indian parties choose Singapore partly because funding is available there.

Kashish added that regulation in India often follows an industry for years, as with wallets and e-pharmacies, and LegalPay aims to follow global best practices so it is ready.

Further reading and sources

Frequently asked questions

What is litigation finance?

Litigation finance is when a third party funds a legal claim in return for a share of the recovery if it succeeds. In LegalPay’s model, the investment is non-recourse, so the client owes nothing if the claim fails. It is aimed at claimants with strong cases but limited cash.

What kinds of cases does LegalPay fund?

Per Kundan, LegalPay focuses on commercial claims between businesses, typically in high courts, the Supreme Court and arbitration. It avoids disputes between individuals, and cases that should take well beyond three years. It does not take on cheque-bounce or family matters at present.

Can retail investors invest in litigation finance?

Kashish said LegalPay launched a pool for upper-retail investors with tickets starting at 25,000 rupees, spread across several arbitration cases. Cases can fail and money can be locked in for years, so read the terms and take independent advice. This is not investment advice.

Conclusion

Kundan and Kashish show how a founder from outside an industry can build in a complex one by combining domain depth, disciplined underwriting and a clear niche. Their focus on business claims and diversified pools is what makes the model work.

If you are in a regulated or unfamiliar space, define what you will not do, build a repeatable diligence process and be open about the risks.

Want more conversations like this? Join The Builders Club, our community of 35,000+ founders and CXOs, and explore more episodes of the Startup Founders Podcast.

Never miss an episode

Join 35,000+ founders and CXOs in The Builders Club community.

Join the Community
Advertisement
Advertisement
Facebook
X
LinkedIn
Silicon Valley VPs vs. Indian Family Business Promoters

The Executive Sponsor Trap: Selling to Silicon Valley VPs vs. Securing Commitments from Indian Family Business Promoters

A Silicon Valley VP can usually sign inside a budget they own. An Indian family business promoter often holds the final say but delegates the evaluation, and that gap is where deals stall. Treating a friendly mid-level sponsor as the decision-maker is the most common mistake in cross-border enterprise sales. Here is how the two models differ and how to secure a commitment that survives promoter review. What is the executive sponsor trap? It is the assumption that the person championing your product has the authority to buy it. In US enterprise sales, a VP or director often does hold budget. In many Indian family-run groups, authority sits with the promoter or family council, while managers and professional CEOs run evaluations. How do US VPs make buying decisions? Delegated authority. A VP typically owns a departmental budget with a defined spending limit. Process-led approval. Procurement and legal run a standard path once a business case is approved. Rep-free research. Buyers do much of their research independently, as shown in Gartner’s 2026 sales survey, so your first call is rarely the start of their evaluation. How do Indian family business promoters make buying decisions? Final say at the top. The promoter or a small family circle may approve significant spend, even when a professional CEO handles daily operations. For context, see Business Today on professional CEOs in Indian business families. Trust over process. A recommendation from a known peer, advisor or existing vendor carries heavy weight. Group thinking. Decisions consider the whole group, not only one business unit, which can slow or accelerate a deal sharply. Tech caution. Research on Indian family businesses by Inc42 describes growth-driven but technology-cautious attitudes, which means proof and references matter. Academic work such as the Indian School of Business research on family business groups offers background on how these groups are structured. Sponsor authority compared: Silicon Valley vs family-run Indian groups Factor Silicon Valley VP Indian family business promoter Budget ownership Often in the VP’s own budget Often approved at group or promoter level Who evaluates The VP’s team Managers, CIO or professional CEO What builds trust Data, ROI case, peer reviews Personal credibility, references, introductions Typical blocker Competing priorities and budget timing No access to the final decision-maker Commitment signal Signed order form Promoter or senior leadership endorsement, then paperwork How do you secure a real commitment from a promoter-led company? Ask the authority question early. “Who gives the final nod on a decision of this size?” is polite and effective. Arrange a senior-to-senior meeting. Your founder or most senior leader meets the decision-maker with the sponsor’s backing. Use a trusted introducer. A mutual contact, existing client or advisor opens doors more reliably than outreach. Give the sponsor a promoter-ready summary. One page covering outcome, risk, cost, and references in plain language. Confirm the paperwork route. Once approval is verbal, ask who triggers legal, security and procurement. What if you cannot reach the promoter? Work through the professional CEO or CIO, and ask them to describe what the promoter will want to see. Prepare that material in advance. FAQ Who makes the final software buying decision in an Indian family-owned business? It varies, but for significant spend the final approval often rests with the promoter or a small family group, while managers and a professional CEO run the evaluation. Ask early who gives the final nod. How is selling to a US VP different from selling to an Indian business promoter? US VPs typically own a budget and follow a defined buying process. Promoters weigh trust, references and group-level considerations, so you need senior access and credible introductions. How do I get a meeting with a promoter or business owner? Use warm introductions from mutual contacts, existing customers, advisors or community events. Ask your internal sponsor to request the meeting and prepare a short, outcome-focused briefing. Conclusion Do not mistake enthusiasm for authority. In the US, test whether your VP owns the budget. In Indian family groups, find the person who gives the final nod, and get there through trusted introductions and a promoter-ready summary. Need warm introductions to promoter-led enterprises? Join The Builders Club. References and further reading Gartner Sales Survey: 67% of B2B buyers prefer a rep-free experience (2026) Gartner: The B2B buying journey and how to optimise it Business Today: Why Indian business families are hiring professional CEOs Inc42: Indian family businesses are growth-driven but tech-cautious Indian School of Business: Family business groups in India About the author: Sohail Khan is Founder and Director of The Builders Club, a professional community of 35,000+ founders and CXOs across India, UAE, Singapore and the US.

Read More »

Why the Self-Serve PLG Playbook Fails with Indian Enterprise CXOs (And the High-Touch Assisted Model That Actually Wins)

Self-serve PLG works when the user is also the buyer. In Indian enterprises, they almost never are. A product-led funnel can get your tool into a team’s hands, but it rarely gets a CXO to sign. The model that wins is a high-touch, assisted motion that uses product usage as proof, not as the whole sales strategy. Here is why the standard playbook stalls in India’s large organisations, and what to run instead. Why does the self-serve PLG playbook fail with Indian enterprise CXOs? Product-led growth, as described by pioneers such as OpenView, assumes that users discover, try and adopt the product themselves, and that revenue follows usage. That assumption holds for tools with low risk, low price and individual buyers. Enterprise buying in India breaks all three conditions at once. The user is not the buyer. An analyst may love your tool. The budget sits with a CIO, CFO or business head who has never opened it. Risk is organisational. A CXO signs against security, vendor-continuity and reputational risk, none of which a free trial answers. Trust is personal. Decisions often move on credibility, references and conversations with someone they respect, not on a sign-up flow. Does a free trial or freemium plan ever work in Indian enterprises? It can work for teams, departments and SMB-sized units, where one manager has a card or small discretionary budget. It rarely scales to the top accounts without a human who turns usage into a business case. What does the high-touch assisted model actually look like? Assisted does not mean old-fashioned. It means every stage of the product experience is paired with a person who removes a specific obstacle. Stage Pure self-serve PLG Assisted model for Indian enterprises Discovery Organic search, product trial Warm introduction, peer room, referral Evaluation Self-guided trial Guided pilot with named success criteria Decision User upgrades with a card Business case built for the CXO and the committee Contracting Click-through terms Negotiated MSA, security review, procurement Expansion In-app prompts Account lead plans rollout across divisions How do you turn product usage into a signed enterprise contract? Use the product as the evidence, and a person as the translator. A practical sequence: Find your champion. Identify the user who gets the most value and ask them to explain the problem in their own words. Quantify the result. Convert usage into time saved, errors avoided or revenue influenced, in a one-page summary the CXO can read in two minutes. Map the buying committee. Ask your champion who else must say yes: IT, security, finance, legal, and the business owner. Run an executive conversation. A founder or senior lead speaks to the CXO about outcomes and risk, not features. Offer a scoped commitment. A defined pilot or first-division rollout with clear exit and expansion terms reduces perceived risk. When should you still invest in self-serve? Do not abandon it. Use self-serve as the top of the funnel and as a signal engine. Track which accounts have several active users, which teams invite colleagues, and which admins explore security settings. Those are the accounts your sales team should call first. Think of it as product-qualified leads feeding a human-led close. Many global companies now run exactly this hybrid, and it fits Indian enterprise buying better than a pure self-serve approach. FAQ Is PLG dead for B2B SaaS in India? No. PLG is useful for building awareness, usage data and champions inside accounts. It fails as the only motion for large enterprises, where committees, security reviews and relationships decide the contract. A hybrid model works better. What is a product-qualified lead (PQL)? A PQL is an account or user whose in-product behaviour suggests buying intent, such as multiple active teammates or admin-level exploration. Sales teams use PQLs to prioritise who to approach with a human conversation. How many people does an assisted enterprise sale need? It depends on deal size, but you typically need one senior owner for the relationship, one technical resource for security and integration questions, and a customer success lead after signing. Founders often cover the first two roles in early deals. Conclusion PLG gets you into the room, but it does not get a CXO to sign. In Indian enterprises, winning sales pair product evidence with human trust: a champion, a business case, a guided pilot and a senior conversation. Building an assisted enterprise motion? Meet founders and CXOs who have done it at The Builders Club, and bring your toughest sales question to our next roundtable. Join The Builders Club. About the author: Sohail Khan is Founder and Director of The Builders Club, a professional community of 35,000+ founders and CXOs across India, UAE, Singapore and the US.

Read More »