// PODCAST

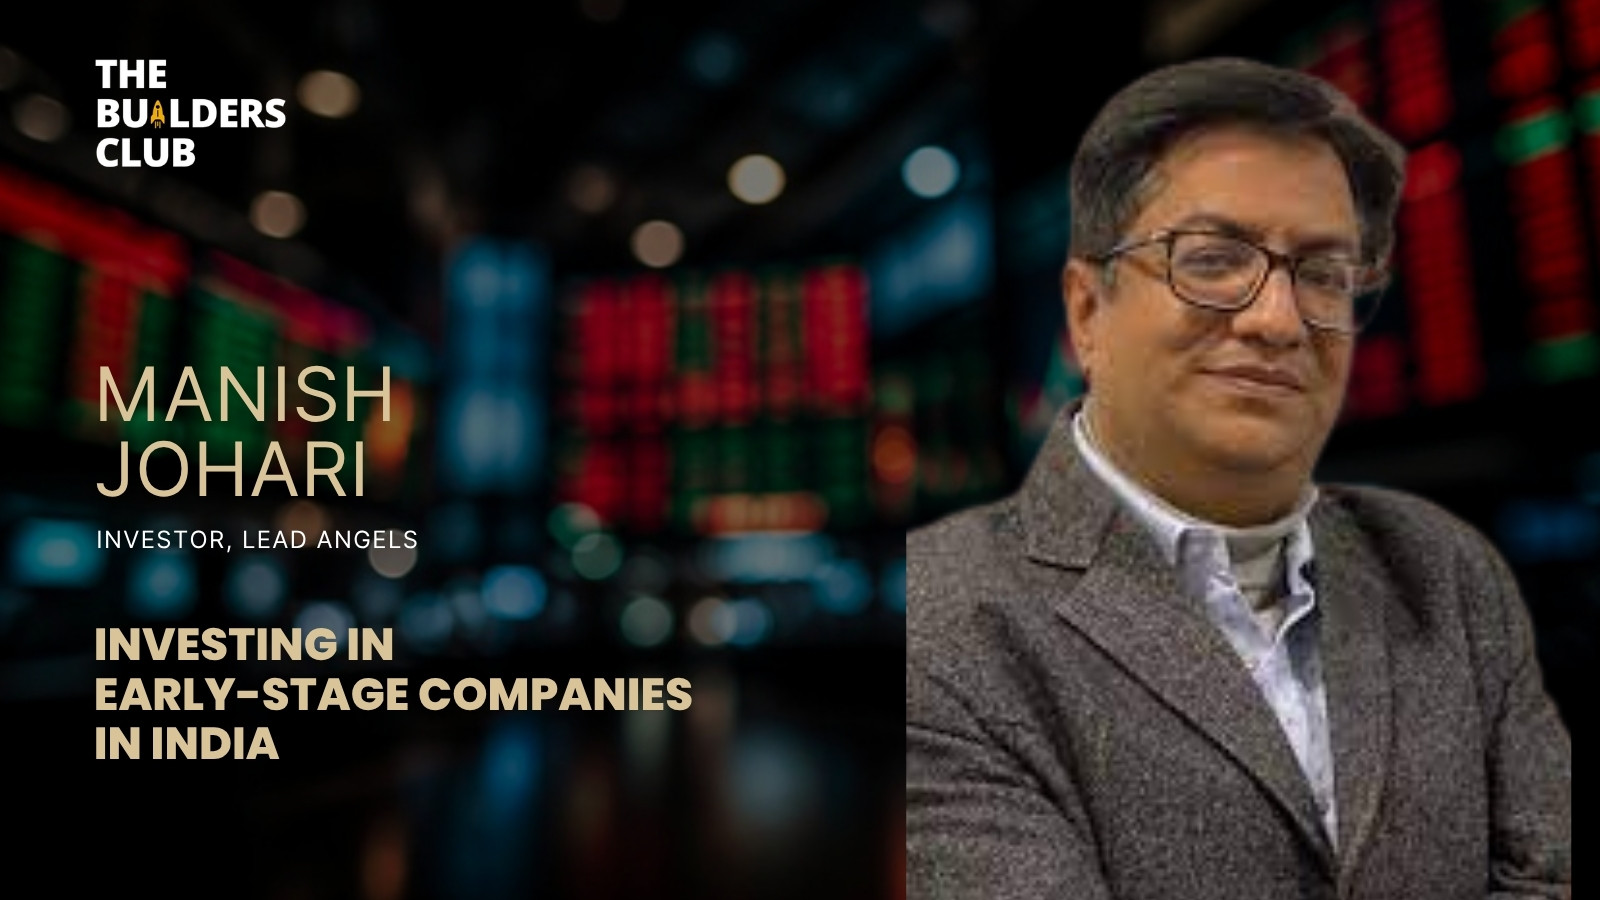
How Investors Think: Angel Investing Maths for Founders | Manish Johari, Lead Angels

Manish Johari, who has spent 25 years across private equity, VC and angel networks, explains how investors evaluate startups, build portfolios and think about returns.
Manish Johari, Lead Angels on The Builders Club Startup Founders Podcast
Advertisement

Most founders pitch what they have built. Investors listen for something else: a real problem, a defensible edge and a believable path to an exit.

In this episode, Manish Johari, a 25-year veteran of private equity, venture capital and angel investing, shows how investors think from the other side of the table, including the maths behind angel portfolios.

How do investors think about startups? Manish Johari’s core view

Manish Johari has worked with Agility Ventures, Lead Angels and Maple Capital Advisors. His view is that investors back startups that solve a real problem, stay focused and can exit at a meaningful multiple within a few years.

He also argues that founders overestimate how much funding and glamour define a startup. Plenty of strong businesses grow on their own capital, while the ones that raise money are signing up for a treadmill of rapid scaling.

  • Solve a real problem. He prefers companies that serve genuine needs, such as vernacular-language learning for kids and inputs for marginal farmers.
  • Look for a moat. An unfair advantage, such as customer lock-in or a community people stay in, matters more than a clever idea.
  • Stay focused. A single-purpose company is easier to scale, to fund and to acquire.
  • Know the exit maths. An angel investor typically looks for an exit in four to five years at a minimum of 10x.

What are investors actually looking for in a startup?

Manish says the first filter is whether the founder is solving a real problem for a real customer segment. He points to investments aimed at the base of the pyramid, where the problem is obvious and the demand is hard to fake.

The second filter is a moat. He refers to the unfair advantage box in the lean canvas and says it does not have to be a patent. Lock-in with customers, such as the way users rarely abandon an email account once their storage fills up, can be just as strong.

  • A problem that customers feel strongly.
  • Market size and scalability.
  • A defensible advantage that competitors cannot copy quickly.
  • Healthy repeat behaviour: customer repeat rate, churn and usage patterns.

Does a startup need high margins and a community to attract funding?

Manish says investors tolerate losses only when something else is building up. He uses the razor and blade model as the example: a product that brings customers back to buy something else.

He also describes how platforms like WhatsApp, Facebook and Prime became valuable by hooking a community first and monetising later. His takeaway for founders is to ask whether the community or user base would be exciting to a larger buyer.

Why margins still matter

He recalls that at Lead Angels a business with a gross margin below about 70 percent would not get a look. Thin-margin delivery models only work, in his view, when they sit inside a larger ecosystem.

Why is focus so important for founders?

Manish says resources are limited, so a startup has to concentrate on one thing and deliver real value there. He cites the odds he quotes: roughly 90 percent of startups fail, and of those that succeed, more than 60 percent changed drastically from their original plan.

His advice is to move from plan A to a plan that works before the runway runs out.

  • Set fixed parameters for your product and stay flexible only within them.
  • Do not chase every customer request. Apple dropping the headphone jack is his example of a firm product call.
  • Indian founders, he says, often over-please customers and forget why they built the product.

How should founders think about fundraising and runway?

His blunt answer is that a founder is always raising. He recommends raising enough to last around 18 months, then starting to talk to investors again well before the money runs low.

He also advises staying in touch with investors who say no. Update them on progress, since many will come around once you have hit your milestones.

  1. Raise enough capital for roughly 18 months of runway.
  2. Prove your milestones during that window.
  3. Keep investors updated even when you are not formally raising.
  4. Start the next round while you still have months of cash left.

How does angel investing maths work?

For an angel, Manish looks at a four to five year horizon with a minimum 10x target. Investors can start from as little as 10 lakh rupees a year, and he suggests spreading it across four to six investments.

Over about three years he suggests building a portfolio of 15 to 20 companies, because many will fail. In his example, around 40 percent of a 15-company portfolio dies, one company returns 20x and the rest return around 2x, which is enough to return the fund.

  • Allocate roughly 5 to 8 percent of your investable portfolio to startups, and no more than 10 percent.
  • Expect a high mortality rate even with careful due diligence.
  • Due diligence should cover compliance too, such as unpaid taxes that become a liability.

How does an angel network or VC firm work inside?

Manish describes several teams: investor relations to bring in new limited partners and angels, curation of deals, and portfolio management. After investing, the network helps with hiring, funding and marketing expertise.

Lead Angels also has an arm that helps portfolio companies raise follow-on rounds from external funds.

Further reading and sources

Frequently asked questions

How much money do I need to start angel investing in India?

Manish Johari says you can start from around 10 lakh rupees a year. He suggests spreading that across four to six startups rather than concentrating on one.

What returns do angel investors expect from a startup?

He looks for an exit within four to five years at a minimum of 10x on each investment. He expects many companies to fail, so a single 20x winner is what returns the fund.

How much of my portfolio should go into startups?

He suggests 5 to 8 percent of your investable portfolio, and no more than 10 percent even for higher risk appetites. Startups are a high-mortality asset class.

Conclusion

Investors reward founders who solve a real problem, build a moat and stay focused. They also think in portfolio maths, so your job is to show how you could be the 20x outcome.

Before your next pitch, check your margins, your repeat customer behaviour and your runway plan, and keep your investors updated between rounds.

Want more conversations like this? Join The Builders Club, our community of 35,000+ founders and CXOs, and explore more episodes of the Startup Founders Podcast.

Never miss an episode

Join 35,000+ founders and CXOs in The Builders Club community.

Join the Community
Advertisement
Advertisement
Facebook
X
LinkedIn
Land and Expand: Western Tech vs. Tier-1 Indian Enterprises

Dissecting the ‘Land and Expand’ Thesis: Upsell Velocities Inside Western Tech Companies vs. Tier-1 Indian Enterprises

Land and expand works in both markets, but the engine is different. In Western tech companies, expansion follows usage and seat growth. In Tier-1 Indian enterprises, expansion follows trust and new approvals. Forecasting both with the same upsell curve will overstate one and understate the other. This post explains the mechanics so you can plan a realistic expansion path. What is the land and expand model? Land and expand means winning a small initial deal, proving value, then growing contract value through more users, modules or business units. Its success is measured by net revenue retention, discussed in McKinsey’s research on NRR in B2B tech. Note: public benchmarks on upsell velocity by geography are scarce. Treat the comparisons below as structural patterns and use your own cohort data. How does expansion happen inside Western tech companies? Usage-triggered growth. Teams add seats or tiers as adoption spreads. Budgets are often held by team leads. Self-serve upgrades. Smaller expansions may not need a new procurement cycle. Faster internal referrals. Peer teams within the same company often adopt tools they see colleagues using. How does expansion happen inside Tier-1 Indian enterprises? Approval-triggered growth. Each new business unit may need its own sponsor, budget and sometimes a fresh security review. Relationship-led referrals. A senior leader introducing you to another division is worth more than usage data alone. Group-level frameworks. Once you are an approved group vendor, onboarding additional entities can become faster, which is where the expansion curve steepens. Lumpy rather than linear. Expansion often arrives as a step change after a successful quarter or leadership review. Expansion velocity compared: Western tech vs Tier-1 Indian enterprises Factor Western tech company Tier-1 Indian enterprise Expansion trigger Usage and seat growth New sponsor, new division, new approval Early pace Faster, often incremental Slower, often step-wise Long-run potential Capped by company size and seat count Can be large across group entities Main accelerator Product adoption Executive sponsorship and group vendor approval Main risk Downgrades and consolidation Stalled approvals between divisions How do you build an expansion plan that fits the market? Define the expansion map at landing. List every division, entity and use case that could adopt the product. Turn the first win into a reference. A short, approved case study is portable across divisions. Get group-level approval where possible. A master agreement or empanelment can shorten later onboarding. Assign an expansion owner. Do not leave growth to support staff. Forecast in stages. Model Indian expansion as step changes tied to approvals, not as a smooth monthly curve. When should you stop investing in an account? If, after two quarters, you still have only one sponsor, no group-level visibility and no referral, expansion is unlikely. Shift effort to accounts with multiple advocates. FAQ What is land and expand in enterprise SaaS? It is a model where a vendor wins a small first contract, proves value and then grows revenue through more users, modules or business units. Success is measured by net revenue retention. Is land and expand slower in India? Early expansion is often slower because each division may need separate approvals, but it can accelerate sharply once you are an approved group vendor with senior sponsors. How do I plan an upsell forecast for Indian enterprises? Model expansion as step changes linked to specific approvals, new divisions and executive reviews. Use your own historical cohorts rather than a generic monthly growth rate. Conclusion Land and expand is a durable strategy in both markets, but the triggers differ. Western accounts grow with adoption. Indian enterprise accounts grow with trust and approvals. Plan the expansion map before you land, and forecast in steps. Want to learn how other founders expanded across Indian business groups? Join The Builders Club. References and further reading McKinsey: The net revenue retention advantage in B2B tech Harvard Business Review: The risks of prioritising short-term revenue over customer fit Harvard Business Review: Winning the right customers isn’t just a sales issue Gartner: The B2B buying journey and how to optimise it NASSCOM-Frost: Enterprise digital transformation About the author: Sohail Khan is Founder and Director of The Builders Club, a professional community of 35,000+ founders and CXOs across India, UAE, Singapore and the US.

Read More »

The Paid Pilot Showdown: Do Proof-of-Concepts Convert Better in Western Markets or Indian Enterprises?

A paid pilot is not a free trial with an invoice. It is a commercial test with a pre-agreed definition of success. In many Western markets, buyers are used to paying for pilots and expect a go or no-go decision at the end. In many Indian enterprises, pilots are still run as free evaluations that drift for months with no clear path to a contract. Here is how the two approaches differ, why conversion rates are hard to compare, and how to run a pilot that actually ends in a signature. What is a paid pilot, and how is it different from a PoC? A proof of concept (PoC) tests whether something is technically possible. A paid pilot tests whether it creates business value in a real environment, with real users, under a commercial agreement. The word “paid” matters because payment forces a budget owner, a scope and a decision date. Without those, a pilot becomes a long free service. Note: there is no reliable public dataset comparing PoC-to-contract rates between Western and Indian enterprises. The patterns below come from how buying processes typically work, so measure your own conversion rate and treat it as your benchmark. How do pilots typically run in Western markets? Budget exists for experimentation. Innovation or departmental budgets often fund pilots, so charging a fee is accepted. Success criteria are written down. Metrics, timelines and the decision-maker are agreed before kickoff. Procurement has a pilot template. Many large buyers have standard pilot or evaluation agreements, which shortens legal time. Outcome is a decision. Convert, extend with conditions, or stop. How do pilots typically run in Indian enterprises? Free evaluation is the default expectation. Teams often ask vendors to prove value before any money moves. Sponsor is clear, budget is not. The business head may love the pilot, while the commercial approval sits elsewhere. Scope expands quietly. Extra integrations, extra users and extra reports get added without changing the commercial terms. Timeline is relationship-led. Decisions follow internal bandwidth, leadership changes and budget cycles, not just pilot results. Western vs Indian pilots: where do conversion rates diverge? Dimension Typical Western enterprise Typical Indian enterprise Pilot fee Commonly accepted Often resisted; may be credited against the contract Success criteria Documented up front Often verbal or evolving Decision owner Named budget holder Sponsor plus a wider approval chain Main failure mode Pilot succeeds but loses to priorities Pilot drags on without a decision Best protection Clear exit criteria Commercial conversion terms signed first The key insight is that conversion depends less on market and more on pilot design. A well-structured pilot in either country converts better than a loose one. How do you design a pilot that converts in India? Agree on the business problem, not the feature list. Write the one metric the sponsor will defend internally. Set a fixed duration. Typically 4 to 12 weeks, depending on integration depth. Put an end date in writing. Charge something. If a full fee is not possible, charge a partial fee that is credited against the first-year contract. Even a nominal commitment signals seriousness. Pre-agree the conversion path. State the commercial terms that apply if success criteria are met, so the next step is a signature rather than a new negotiation. Name every approver early. Identify IT, security, finance and procurement stakeholders while the pilot is running, not after. Hold a formal readout. Present results to the sponsor and the decision-maker together, with a clear recommendation. What are red flags that a pilot will not convert? No budget owner has attended a single meeting. The success metric keeps changing. Requests for new features appear mid-pilot with no change in scope or fees. The sponsor cannot name the next approval step. FAQ Should Indian startups charge for pilots? Wherever possible, yes, even partially. A paid or credited pilot filters out casual evaluations and pushes the buyer to identify a budget and a decision-maker. If a fee is impossible, require a signed pilot agreement with success criteria and a conversion clause. How long should an enterprise pilot last? Most pilots work best between 4 and 12 weeks, based on integration complexity. Longer pilots often lose momentum. Set a fixed end date and a decision meeting in the calendar before you start. What is a good PoC-to-contract conversion rate? There is no universal benchmark. Track your own rate across your first 10 pilots, split by whether they were paid, credited or free. That internal comparison is more useful than any generic industry figure. Conclusion Pilots convert when they are designed as commercial decisions. Define success in writing, attach a fee or credit, fix the timeline, and agree on the conversion path before the first login. Do that, and the Western-versus-Indian gap narrows considerably. Want pilot templates and peer advice? Join The Builders Club to learn how founders structure pilots with large enterprises. Join the community. About the author: Sohail Khan is Founder and Director of The Builders Club, a professional community of 35,000+ founders and CXOs across India, UAE, Singapore and the US.

Read More »